

Overall trends
Rising prices on the secondary market
The latest figures from the secondary market for fine wine show a market gaining ground in several areas. Looking at the leading price index, the Liv-ex Fine Wine100, which tracks the 100 most sought-after wines on the secondary market, the trend is clear: prices are rising. Not dramatically, but the curve is pointing firmly upward. The index is up 2.1% this year and 4.4% over the past 12 months. This gives sellers on the marketplace a tailwind and an even stronger incentive to sell from their collections.
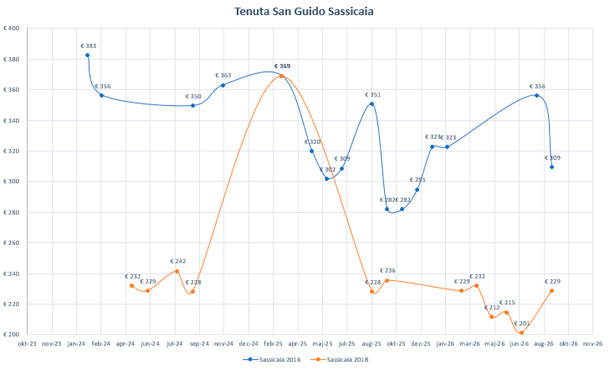
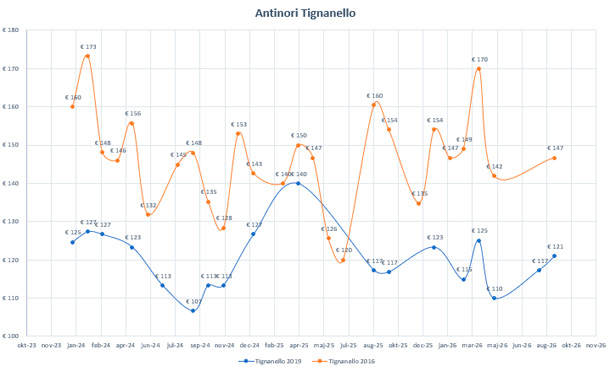
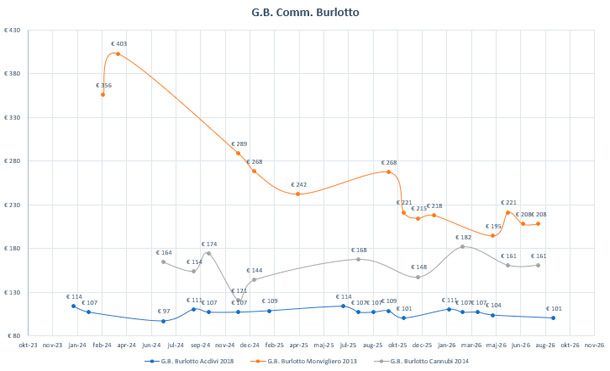
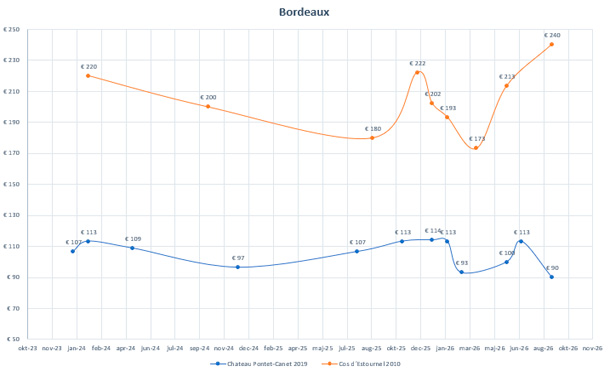
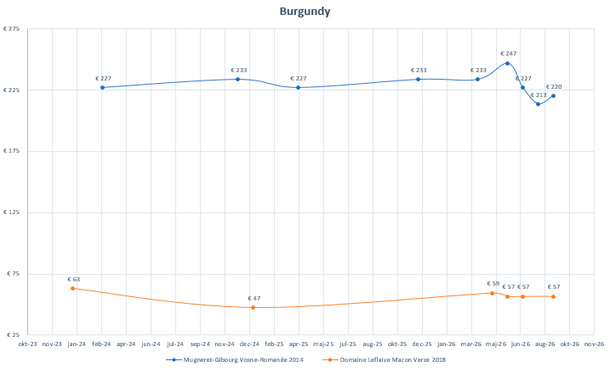
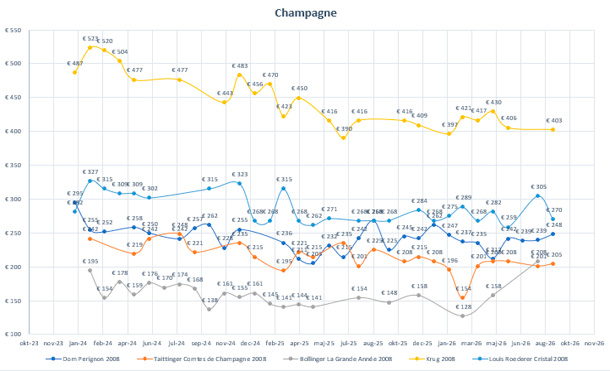
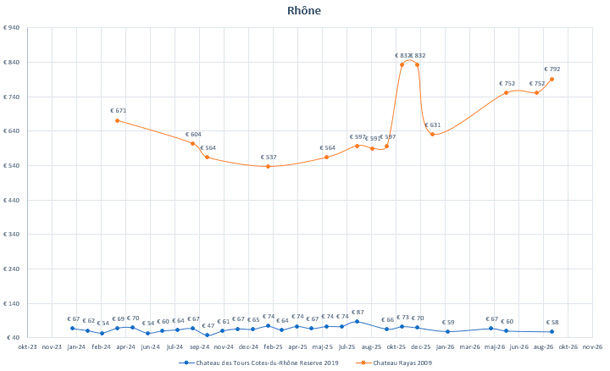
Prices on ShareWine are following the same trend, with increases across several categories. It is worth noting that large price fluctuations in some of this report's charts are typically driven by the seller's sales strategy, the timing of the listing, good photos and the chosen starting price. A markedly higher sale price is therefore more likely a sign that the seller succeeded in engaging many potential buyers who drove the price up, rather than a general price increase for that particular wine.
High trading activity and continued growth in France
Overall, activity was very strong in the third quarter, with 42% more trades completed on ShareWine than in the same quarter of 2025. Historically, trading activity tends to dip in Q3 because of the summer holidays, but this year told a different story. The number of trades actually rose 2% from Q2 to Q3, breaking the usual pattern. Our wine enthusiasts most likely took their summer holidays this year too, so we believe the influx of new wine-loving members over the summer is what lifted activity during the quarter.
The French market in particular continues its impressive growth. One year after our launch in France, more than 1,000 new French wine enthusiasts have joined the community, including both private and professional buyers and sellers.
The right listing format drives more sales
This year, we have focused on better guiding our sellers as they choose between fixed-price and auction formats when creating listings. In last quarter's trend report, we shared that sellers had become better at using the strengths of each listing format and, as a result, were achieving more sales. That development continued through Q3, with significantly more wine once again traded at fixed prices, and a higher share of auctions selling the first time around without being relisted.
At the same time, improved options for filtering by auctions or fixed-price listings have made it easier for buyers to find exactly the wines they are looking for.
Regional trends
Italy
Let's start in Italy, which performed impressively overall in Q3. The number of trades in wines from Piemonte held steady compared with the previous quarter, while Tuscany lifted the region with 19% more trades in Q3. Italy remains on a positive trajectory, with plenty of exciting wines for sale at every price point, and year to date, 40% more trades have been completed than in the same period of 2025.
Prices for Italian wine on the secondary market are generally rising. Year to date, the Italy100 price index is up 3.5%, and over the past 12 months, it has risen 4.9%.
Below you can see the price development on ShareWine for Antinori Tignanello 2016 and 2019, Tenuta San Guido Sassicaia 2016 and 2018, as well as three wines from Barolo producer G.B. Comm. Burlotto: Acclivi 2018, Monvigliero 2013 and Cannubi 2014.
Bordeaux
The third quarter has undoubtedly been challenging for winemakers in Bordeaux, where severe wildfires came alarmingly close to the vineyards. Everyone is now waiting to see what impact the smoke has had on this year's grapes.
On ShareWine, the number of Bordeaux trades was 3% higher than in the previous quarter, and year to date, 1% more trades have been completed than in the same period of 2025.
Price development on the global secondary market also shows a fairly stable picture for Bordeaux, with the Bordeaux500 index down -0.2% year to date.
Below you can see the price development for Château Cos d'Estournel 2010 and Château Pontet-Canet 2019.
Burgundy
Moving on to the marketplace's largest category, the number of Burgundy trades rose 7% in Q3. Year to date, 37% more trades have been completed than in the same period of 2025.
The Burgundy150 price index is also climbing slowly but steadily. Year to date, prices are up 1.7%, and over a 12-month period, Burgundy prices have risen 2.8%.
Below you can see the price development over time on ShareWine for a bottle of Domaine Leflaive Mâcon-Verzé 2018 and Domaine Mugneret-Gibourg Vosne-Romanée 2014.
Champagne
Champagne is among the fastest-growing categories on the marketplace, and year to date, 47% more Champagne trades have been completed than in the same period of 2025.
Prices are on the rise here too. Year to date, the Champagne50 price index, which tracks the 16 most traded Champagnes on the secondary market, is up 4.1%.
Below we follow the price development of the 2008 vintage from five renowned Champagne houses. Krug is declining and Bollinger is rising, while the others remain more or less stable.
Rhône
The number of trades in Rhône wines fell for the second consecutive quarter and was -2% lower than in Q2. Year to date, however, the number of trades is roughly in line with the same period of 2025, and it will be exciting to follow developments in Q4, when historically, slightly more Rhône wine is always traded.
The Rhône100 index has remained flat throughout 2026 and closes Q3 with a modest increase of 0.5% year to date.
Below you can see the price development of two selected Rhône wines in two different price segments on the marketplace. Château Rayas is especially interesting to follow, as both demand and price are rising, and the wine is now selling at its highest level in several years.
Thank you for reading
These are the trends we have chosen to focus on this time. We look forward to following developments in Q4 and taking stock of 2026 in the next edition of ShareWine Trends, which will be published in January.
Thank you for reading, and happy trading. 🍷
Mikkel Lomholt
Founder of ShareWine